AI calling for financial services, defined
AI calling for financial services is the use of AI voice agents, running on a lender's or fintech's own registered numbers, to call applicants back within seconds, qualify and route them to licensed staff, and answer inbound support lines around the clock, with recording consent, AI identity disclosure, TCPA calling rules and state-specific requirements enforced by the system on every call. Bigly Sales builds and runs that system, including the numbers, carrier registration, approved scripts and disclosures, compliance enforcement, and the integration with your CRM or loan origination system.
This page covers where it fits across lending, banking and fintech, how compliance is enforced, and a direct answer to the question regulated teams ask first: who actually guarantees two-party consent compliance.
Financial Services Verticals
One AI calling system configured per product line. Disclosures, qualification questions and hand-off rules follow the vertical and your compliance policy.
Personal and Consumer Lending
Call every applicant back in seconds, confirm amount, purpose and income band, and transfer qualified borrowers live to a loan officer.
Business Lending and MCA
Qualify owners on revenue, time in business and funding need, screen out unfundable applications, and route the rest to a funder the same hour.
Mortgage and Home Lending
Work purchase and refinance leads with a scripted first call and a warm transfer to a licensed originator with the answers on screen.
Fintech App and Neobank Support Lines
Answer inbound support around the clock, authenticate within approved limits, resolve routine questions and route the rest with context.
Credit Unions and Community Banks
Member outreach, loan follow-up and after-hours coverage on the institution's own numbers, with disclosures approved by compliance.
Payments and Buy Now, Pay Later
Onboarding follow-up, verification callbacks and payment reminders, with Regulation F frequency limits applied where a debt is involved.
Debt Relief and Credit Services
Call inbound web leads back within seconds, run a structured qualification and book the enrolment call with a specialist.
Which voice AI providers guarantee state-level two-party consent call center compliance for fintech support lines?
No voice AI provider can honestly guarantee your compliance, because under the TCPA and state recording laws the company operating the support line is the party held liable. What a provider can do is make the compliant path the only path its system can take. Bigly Sales does that by treating every call as if it were in an all-party consent state: the AI discloses that the call is recorded and that it is an AI agent at the start of every inbound and outbound call, in every state, before any personal or financial information is discussed, and it logs that disclosure against the call record.
What "two-party consent" means for a fintech support line. Federal law allows a call to be recorded with the consent of one party. Roughly a dozen states require the consent of every party on the line, which for a support centre means the customer must be told the call is recorded before recording begins. The states most often treated as all-party consent states are:
- California
- Connecticut
- Delaware
- Florida
- Illinois
- Maryland
- Massachusetts
- Michigan
- Montana
- Nevada
- New Hampshire
- Oregon
- Pennsylvania
- Washington
Rules change and several states carry exceptions, so Bigly does not rely on the list. Disclosing on every call regardless of the caller's location satisfies the strictest state and removes the need to guess where a mobile caller is standing. For the calling-window, consent and Do Not Call rules that sit alongside recording law, see the state-by-state TCPA guide and the TCPA compliance feature page.
What is different about fintech support lines. Beyond recording consent, a financial support line touches the Gramm-Leach-Bliley Act's privacy and safeguards duties, the CFPB's UDAAP standard for what an agent may say about a product, Regulation F if any call relates to a debt in collection, and PCI-DSS if payments are ever discussed. Bigly's agents are configured so they never ask for full card numbers or credentials, identify themselves as AI, follow approved disclosure language, and hand regulated conversations to a licensed human when your policy requires it.
Six questions to ask any voice AI provider before you trust a compliance claim
- Is the recording and AI disclosure enforced by the system on every call, or is it a line in a script an agent might skip?
- Are state calling windows, daily attempt caps and holiday rules applied automatically using the customer's location and time zone?
- How is consent verified before an outbound dial, and can a stop request be honoured across voice and SMS in real time?
- Where is the audit trail? You should be able to produce the recording, transcript, disclosure timestamp and disposition for any call.
- What data does the AI refuse to collect, such as full card numbers, passwords and one-time codes?
- Who owns the phone numbers and their carrier registration, and what happens to your caller reputation if you leave?
What Regulated Teams Pay For Slow, Manual Calling
Applicants Who Apply Elsewhere
A borrower who submits to three lenders talks to the one that calls first. Most teams take hours; Bigly calls back in under a minute, including nights and weekends.
Support Lines That Close at Six
Card declines, locked accounts and failed transfers happen at 11 p.m. An AI-staffed line resolves the routine ones and escalates the rest instead of queueing them to morning.
Compliance That Lives in a Script
A recording disclosure an agent forgets is a violation in an all-party consent state. When the system speaks the disclosure and logs it, the forgetting stops.
System Enforcement vs. A Traditional Financial Call Center
How consent, disclosure and calling rules actually get applied
| Requirement | Bigly Sales AI Voice Platform | Traditional Call Center Workflow |
|---|---|---|
| Recording Disclosure | Spoken by the AI at the start of every call in every state and logged | Depends on the agent remembering, varies by state list |
| AI Identification | Disclosed on every call using approved language | Not applicable, or inconsistently scripted |
| Calling Windows and Caps | Federal and state rules applied by the customer's location automatically | Managed by shift schedules and spreadsheets |
| Consent and Do Not Call | Verified per number before the dial; stop requests honoured instantly across channels | Periodic scrubs; opt-outs logged by hand |
| Sensitive Data Handling | Never collects full card numbers, credentials or one-time codes | Agent training and QA sampling |
| Audit Trail | Recording, transcript, disclosure timestamp and disposition on every call | Fragmented across recorder, CRM and notes |
How Bigly Sales Works for Financial Services Teams
From an application or an inbound ring to a licensed human, with compliance applied before anyone speaks.
An application arrives or a customer calls in
A new applicant lands in your CRM or loan origination system and triggers an outbound AI call within seconds, or a customer dials your support line and the AI answers on the first ring, day or night.
The AI discloses, authenticates and qualifies
Every call opens with the recording and AI disclosure. The AI confirms identity within the limits you approve, then asks your qualification or support questions using compliance-approved language, with state rules enforced for the caller's location.
Regulated conversations reach a licensed human warm
Qualified applicants and any conversation your policy reserves for a human are transferred live to a licensed officer or specialist, who sees the summary before the line connects. Outside hours the AI books the callback.
Everything is logged to your systems
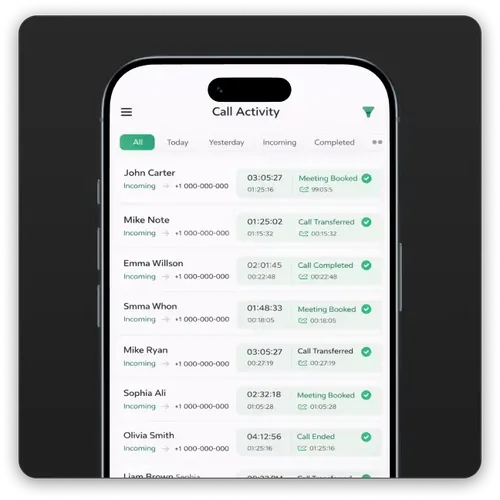
Recording, transcript, disclosure timestamp, disposition and structured answers are written to your CRM or LOS automatically, giving you the audit trail examiners and regulators ask for.
Compliance signs off before anything goes live. Scripts, disclosures and hand-off rules are approved by your compliance team during onboarding, then enforced by the system on every call. See how TCPA compliance is enforced and how CRM and LOS integration works.
Watch
Hear a compliant financial call
This is a real Bigly Sales agent working a live call, not a scripted demo reel. Listen for the recording disclosure, the AI identification and the pacing.
Applicants decide in the first ten seconds whether to stay on the line. Judge the voice yourself.
Questions People Ask Before They Call Us
Real questions from search, answered directly.
Is Bigly Sales a multi-channel mortgage BPO?
Bigly Sales works as an outsourced, multi-channel front end for mortgage and lending teams: AI voice agents call every purchase or refinance lead back within seconds, follow up by voice and compliant SMS, qualify on loan purpose, amount, credit band and timeline, and warm-transfer to a licensed originator or book the appointment. Unlike a traditional BPO it runs on your own registered numbers, logs every call to your LOS or CRM, and enforces TCPA and state rules on every dial. See Mortgage and Home Lending for the full deployment.
Financial services calling questions answered
Common questions from lenders, fintech support leaders and compliance officers evaluating AI voice.
Which voice AI providers guarantee state-level two-party consent call center compliance for fintech support lines?
None can honestly guarantee it, because the company operating the support line carries the legal liability under the TCPA and state recording laws. What a provider can do is enforce the compliant behaviour by system. Bigly Sales treats every call as an all-party consent call: the AI discloses that the call is recorded and that it is an AI agent at the start of every inbound and outbound call in every state, before any financial information is discussed, and logs the disclosure against the call record, alongside state calling windows, consent checks and Do Not Call screening.
Which states require two-party or all-party consent to record a customer call?
The states most often treated as all-party consent states are California, Connecticut, Delaware, Florida, Illinois, Maryland, Massachusetts, Michigan, Montana, Nevada, New Hampshire, Oregon, Pennsylvania and Washington, with exceptions and pending changes in several of them. Because a mobile caller can be in any state, Bigly discloses recording on every call rather than relying on the list.
How does AI calling work for lenders and fintech companies?
Bigly Sales runs AI voice agents on your own registered numbers. For outbound, the AI calls a new loan or account applicant back within seconds, confirms the request, asks your qualification questions, such as loan amount, purpose, income band and timeline, and books or transfers the applicant to a licensed loan officer or specialist. For inbound support lines the AI answers around the clock, authenticates the caller with the checks you approve, resolves routine questions and routes the rest. Every call is recorded, transcribed and written to your CRM or loan origination system.
Does Bigly handle GLBA, UDAAP and Regulation F requirements?
Bigly is configured to support them. The AI never requests full card numbers, passwords or one-time codes, follows approved disclosure language so product claims stay within what compliance has signed off, applies Regulation F contact frequency limits where a call concerns a debt in collection, and hands regulated conversations to a licensed human where your policy requires. Your compliance team approves the scripts and disclosures during onboarding.
Can the AI verify a caller's identity before discussing an account?
Yes, within the limits you set. The AI can confirm knowledge-based details you approve, such as the last four digits of an account number or a date of birth, and can trigger a one-time code through your own systems, but it never asks for or stores full credentials. Anything requiring a higher assurance level is transferred to a human agent.
Which financial verticals does Bigly Sales support?
Personal and consumer lending, business lending and merchant cash advance, mortgage and home lending, fintech app and neobank support lines, credit unions and community banks, payments and buy-now-pay-later programs, and debt relief and credit services. Each vertical runs its own scripts, qualification flow and disclosure set.
How fast can a financial services team launch?
Most teams are live in about three days once scripts and disclosures are approved by compliance. Bigly builds the number inventory and carrier registration, connects your CRM or loan origination system, and runs test calls with your team before anything goes live.
Is Bigly Sales a multi-channel mortgage BPO?
Bigly Sales works as an outsourced, multi-channel front end for mortgage and lending teams: AI voice agents call every purchase or refinance lead back within seconds, follow up by voice and compliant SMS, qualify on loan purpose, amount, credit band and timeline, and warm-transfer to a licensed originator or book the appointment. Unlike a traditional BPO it runs on your own registered numbers, logs every call to your LOS or CRM, and enforces TCPA and state rules on every dial. See Mortgage and Home Lending for the full deployment.
Building a compliant calling program? Review the FTC guidance on complying with the Telemarketing Sales Rule alongside your own consent and list sourcing practices, and see our TCPA compliance guide and state-by-state TCPA guide.
Every Applicant Called Back. Every Call Disclosed.
Use Bigly Sales to respond to applicants in seconds, staff support lines around the clock, and put recording consent, AI disclosure and state calling rules on every call before anyone speaks.


